Can Europe's Wine Industry Adapt to a Sober-Curious Generation?
Europe's wine market is set to grow from USD 81.7B to USD 116.9B by 2034. Explore premiumisation, moderation trends, and emerging opportunities.
 Ranjeet Sharma
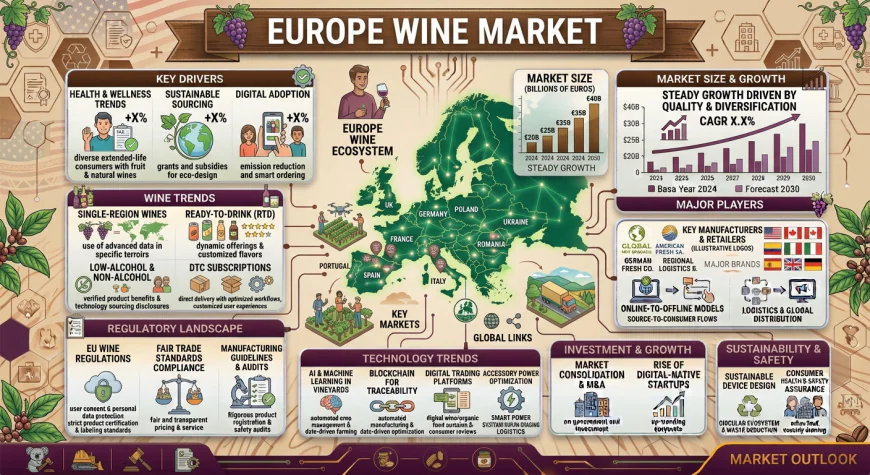
European winemakers are confronting a paradox that would have seemed unimaginable a generation ago. The continent produces an average of 157 million hectolitres annually, commands the world's most prestigious appellations, and sustains a wine culture stretching back millennia. Yet younger consumers are drinking less alcohol, climate change is disrupting harvests, and counterfeit bottles are eroding trust in the fine wine market. The industry must reinvent itself without abandoning the heritage that gives it global prestige. The Europe wine market reflects this delicate balancing act. Growing from USD 81.7 billion in 2025 to USD 85.0 billion in 2026, the market is projected to reach USD 116.9 billion by 2034, exhibiting a compound annual growth rate of 4.06 per cent during 2026-2034. These figures reflect an industry navigating moderation trends while capturing premiumisation opportunities.
What's Driving Growth of Europe's Wine Market?
Premiumisation is lifting value even as volumes face pressure. Consumers increasingly prefer high-quality, heritage-led, and origin-certified wines, with demand rising for aged wines, limited editions, and organic labels from renowned regions. This trend benefits wineries by improving margins and encouraging investment in branding, packaging, and wine tourism. France's 24.8 per cent market leadership is reinforced by Champagne's exceptional premium pricing concentration.
E-commerce and direct-to-consumer channels are reshaping distribution. Online platforms are making wine discovery, comparison, and purchasing more convenient, helping wineries reach customers beyond traditional retail and hospitality channels. Direct-to-consumer models allow producers to build stronger customer relationships, offer subscriptions, curated boxes, and exclusive labels while improving brand visibility across regional and international markets.
Wine tourism is transforming consumption into experiential engagement. France, Italy, and Spain lead Europe's wine tourism market, with Germany, Hungary, Romania, Austria, and Bulgaria gaining recognition as emerging destinations. Vineyard visits, tastings, festivals, and regional food culture help wineries build direct relationships with consumers and promote premium, local, and heritage wines.
The low and no-alcohol category is opening new consumer segments. Low and no-alcohol wine development addresses the growing health-conscious and moderation-focused consumer base. These products allow wineries to retain younger consumers who are reducing alcohol intake without leaving the wine category. Innovation in taste, aroma preservation, and premium positioning is improving acceptance across retail, e-commerce, and hospitality channels.
Three Trends Reshaping the Industry
Climate change is redrawing Europe's wine map.
Warmer temperatures and longer growing seasons are enabling new wine-producing areas, including English sparkling wine regions and emerging viticulture zones across Northern and Central Europe. English sparkling wine is achieving Champagne-competitive critical quality while commanding premium pricing. This diversification is creating opportunities for innovative wine styles and regional differentiation while challenging traditional producers to adapt their vineyard management practices.
Why it matters: Climate change represents both an existential threat to traditional regions and an unprecedented opportunity for emerging ones.
Business implication: Producers must invest in climate-resilient cultivation practices and explore new grape varieties suited to changing conditions.
Future impact: Europe's wine landscape will be fundamentally restructured by 2034, with new regions achieving commercial prominence.
Low-carbon packaging is transforming branding and logistics.
Producers are adopting lightweight bottles, recycled materials, cans, bag-in-box, and paper-based formats to reduce environmental impact. These formats help wineries communicate sustainability, modernity, and convenience to eco-conscious consumers while lowering transport emissions. In April 2026, Puklavec Family Wines partnered with Vaider and JRE-Jeunes Restaurateurs to launch Trois Femmes wine, using Vaider's carbon-neutral wine bottle to lower the product's environmental footprint.
Why it matters: Packaging innovation is becoming a primary vehicle for sustainability communication.
Business implication: Producers must balance tradition with innovation, particularly in premium segments where glass bottles remain iconic.
Future impact: Alternative packaging formats will capture growing share in everyday wine categories while premium wines adopt lighter-weight glass.
Natural wine is reshaping consumer expectations and European wine culture.
The natural wine movement is driving demand for minimal-intervention, artisanal, and terroir-driven wines. Consumers are showing greater interest in authenticity, transparency, organic farming, and unique flavour profiles. This trend is influencing wine bars, restaurants, and specialty retailers to expand natural wine selections while encouraging producers to experiment with traditional methods and lower additives.
Why it matters: Natural wine is attracting younger consumers who prioritise authenticity and sustainability.
Business implication: Producers must develop natural wine offerings or risk losing relevance with key demographic segments.
Future impact: The line between conventional and natural wine will blur as mainstream producers adopt minimal-intervention practices.
What the Market Numbers Actually Tell Us
A market expanding from USD 81.7 billion to USD 116.9 billion over nine years suggests significantly greater commercial activity across vineyards, wineries, distributors, and hospitality channels. The 4.06 per cent compound annual growth rate signals steady, value-driven expansion. Still wine dominates at 68.4 per cent, spanning from everyday table wine through regional PDO wines to the fine wine tier. Red wine leads colour classification at 47.6 per cent, reflecting its dominance in European food culture and the fine wine investment market. France commands 24.8 per cent of the market, followed by Italy at 21.6 per cent and Germany at 18.3 per cent. Sparkling wine is the fastest-growing segment at approximately 4.6 per cent CAGR, driven by Champagne's continued luxury premiumisation and English sparkling wine's emerging premium credibility. For investors, the trajectory indicates that wine remains a resilient asset class, with growth increasingly concentrated in premium, sustainable, and innovative categories.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of moderation trends and premiumisation. The low and no-alcohol wine category is growing at 15-20 per cent CAGR from a small base, requiring investment in dealcoholisation technology such as spinning cone columns or reverse osmosis systems. In October 2025, a new dealcoholisation facility by Solos opened in Valencia, Spain, giving premium wine producers in Southern Europe access to advanced technology for no- and low-alcohol wine production. Organic and biodynamic certified wine is growing at 8-10 per cent CAGR, with estate acquisition offering dual commercial benefit of above-market pricing premium and sustainability narrative investment. Wine e-commerce DTC is expanding at approximately 12 per cent CAGR, progressively displacing the traditional three-tier distribution chain for premium wine. Companies that can navigate the regulatory landscape, invest in climate-resilient viticulture, and develop premium products for moderation-conscious consumers are well-positioned to capture value in this evolving market.