Europe Advanced Wound Care Market Size, Share, Trends and Report 2034
Europe Advanced Wound Care Market reached USD 2.66 Bn in 2025 and USD 2.78 Bn in 2026, forecast to hit USD 3.90 Bn by 2034 at 4.3% CAGR.
 Yadwender Kumar
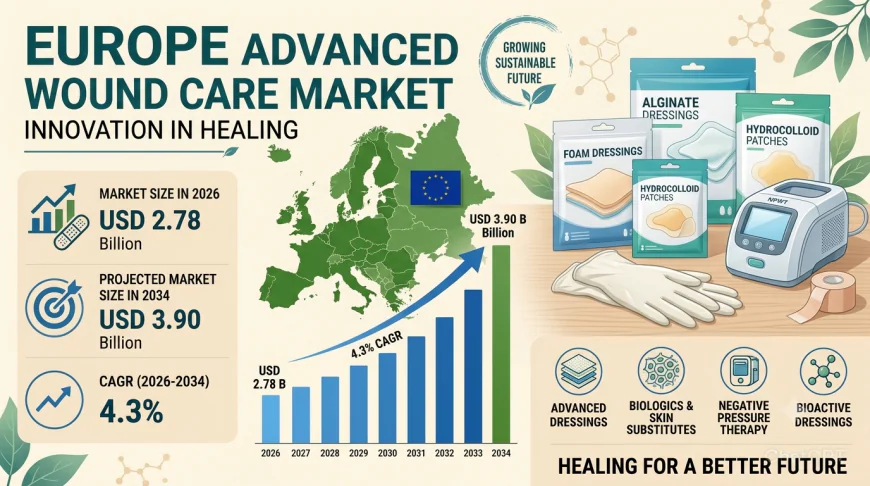
Europe's advanced wound care industry is navigating a landscape of remarkable transformation. For years, wound management across the region relied heavily on traditional dressings and conventional treatment protocols that prioritised basic coverage over active healing intervention. But a convergence of demographic pressure, technological innovation, and evolving healthcare delivery models has arrived with force, reshaping how clinicians, hospitals, and patients approach wound care. Healthcare systems are recording rising chronic wound burdens, manufacturers are accelerating innovation pipelines, and advanced therapeutic solutions are finally overtaking traditional approaches. The Europe advanced wound care market is at the epicentre of this shift. Valued at USD 2.66 Billion in 2025, the market is projected to reach USD 3.90 Billion by 2034, growing at a compound annual rate of 4.3 per cent from 2026 to 2034. These figures reflect an industry entering a new era of clinical maturity.
What's Driving Growth of Europe's Advanced Wound Care Market?
An ageing population is fundamentally reshaping demand for specialised wound management. Europe's demographic evolution, marked by increasing life expectancy and a growing proportion of elderly individuals, drives the advanced wound care market by elevating baseline demand. As of January 2024, the EU population aged 65 and over reached 21.6 per cent, while those aged 80 and above increased to 6.1 per cent, according to Eurostat's 2025 Demography of Europe report. Age-related physiological changes compromise tissue repair and wound healing, making older adults particularly vulnerable to pressure ulcers, venous leg ulcers, and diabetic foot ulcers that require specialised interventions.
The rising prevalence of chronic diseases is compounding the need for advanced therapeutic solutions. Concurrent with demographic shifts, the increasing prevalence of diabetes and cardiovascular disorders exacerbates wound complications, creating a compounded need for advanced therapeutic solutions capable of managing multifactorial healing challenges across healthcare settings. Chronic wounds represent non-healing wounds that fail to progress through normal healing stages within expected timeframes, typically persisting beyond three months despite appropriate treatment. This category encompasses diabetic foot ulcers, venous leg ulcers, pressure ulcers, and arterial ulcers, each presenting distinct pathophysiological challenges requiring specialised management approaches.
Request Sample For PDF Report: https://www.imarcgroup.com/europe-advanced-wound-care-market/requestsample
Technological innovation and clinical evidence generation are broadening treatment possibilities. Ongoing advancements in biomaterials, delivery systems, and therapeutic technologies enhance clinical outcomes while expanding adoption of advanced wound care products. Manufacturers increasingly invest in research to develop dressings with superior antimicrobial activity, improved moisture balance, and bioactive components that actively promote tissue regeneration. In 2025, Rapid Nexus Nanotech Wound Solutions received FDA 510(k) clearance for its Hemastyl gel device, the first to target underlying tissue pathology in chronic wounds. Simultaneously, clinical evidence from randomised trials, real-world studies, and health economic analyses validates these innovations, supporting reimbursement decisions and healthcare professional confidence.
Healthcare systems are prioritising cost-effective wound management strategies. European healthcare systems prioritise cost-effective strategies to address the financial burden of chronic and complex wounds, driving interest in advanced wound care solutions. Although unit costs may be higher than traditional dressings, these products reduce overall care costs by accelerating healing, minimising dressing changes, preventing infections, and lowering hospitalisation rates. Total cost of care approaches, which consider downstream complications like amputations and prolonged stays, favour advanced wound care adoption, as measurable reductions in complications and readmissions demonstrate both clinical and economic value to providers and payers.
Three Trends Reshaping the Industry
Bioactive and regenerative technologies are transforming wound care from passive coverage to active healing.
The advanced wound care sector is witnessing significant innovation through the development and adoption of bioactive wound care products that actively promote tissue regeneration rather than simply providing passive wound coverage. In October 2024, Mölnlycke Health Care acquired Austria's P.G.F. Industry Solutions GmbH, maker of Granudacyn®, enhancing its advanced wound care portfolio and European market presence. Skin substitutes, growth factor applications, and collagen-based matrices are gaining clinical acceptance for managing complex wounds that fail to respond to conventional treatments. These regenerative approaches represent a paradigm shift toward actively stimulating the body's natural healing mechanisms.
Why it matters: The shift toward bioactive products fundamentally changes how wound care protocols must be structured.
Business implication: Manufacturers that fail to invest in regenerative technologies and clinical evidence generation risk losing market share to innovative competitors.
Future impact: The trend toward regenerative approaches will accelerate as clinical evidence demonstrates superior healing outcomes and cost-effectiveness compared to traditional dressings.
Negative pressure wound therapy is expanding beyond hospitals into ambulatory and home care settings.
Negative pressure wound therapy (NPWT) is increasingly moving beyond hospitals into outpatient and home care settings, supported by portable, easy-to-use devices. Its proven effectiveness in accelerating wound healing, minimising infection, and managing complex surgical and traumatic wounds is boosting adoption across multiple clinical areas. Manufacturers are launching single-use disposable systems and advanced smart pumps with wireless connectivity, improving treatment accessibility, enhancing patient compliance, and enabling more convenient, personalised wound care outside traditional clinical environments.
Why it matters: Portable NPWT devices are democratising access to advanced wound therapy beyond traditional hospital settings.
Business implication: Manufacturers must develop user-friendly, portable systems that enable effective wound management in home and outpatient settings.
Future impact: The integration of wireless connectivity and remote monitoring will become standard, enabling data-driven, personalised wound care delivery across care settings.
Ambulatory and home-based wound care is becoming a priority for European healthcare systems.
Healthcare systems across Europe are increasingly emphasising ambulatory and home-based wound care delivery to reduce hospitalisation costs while maintaining treatment quality. In 2025, the Horizon Europe-funded ICAREWOUNDS project launched pilot evaluations of an integrated chronic wound care model across European hospitals, enhancing care pathways, remote monitoring, and primary-specialist coordination. This trend is driving demand for advanced dressings with extended wear times, simplified application procedures, and enhanced patient comfort that enable effective wound management outside institutional settings.
Why it matters: The shift toward home-based care fundamentally changes how wound care products must be designed and distributed.
Business implication: Manufacturers must develop products with extended wear times and simplified application procedures suitable for non-specialist caregivers.
Future impact: Telehealth integration and remote wound assessment technologies will become standard, maintaining clinical oversight while reducing in-person visit requirements.
What the Market Numbers Actually Tell Us
A market expanding from USD 2.66 Billion to USD 3.90 Billion over nine years suggests significantly greater commercial activity across wound care manufacturers, hospital distribution channels, and home care providers. The 4.3 per cent compound annual growth rate signals steady, sustained expansion driven by structural shifts in demographics and healthcare delivery models. The region's advanced wound care industry generated USD 2.66 Billion in revenue in 2025, and this is forecast to rise to USD 2.78 Billion in 2026, setting a new regional benchmark. By 2034, the market could reach USD 3.90 Billion. The dual reality of persistent healthcare budget constraints alongside wound care's emergence as one of the region's most dynamic healthcare segments creates a complex but opportunity-rich environment.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of technology and underpenetrated care settings. The integration of artificial intelligence and machine learning is enhancing user experience by enabling personalised wound assessment and treatment recommendations based on patient data. Germany leads the regional market with approximately 25 per cent share in 2025, supported by advanced healthcare infrastructure, strong reimbursement policies, and significant presence of leading wound care manufacturers. France, the United Kingdom, Italy, and Spain offer substantial medium-term potential. For companies that can navigate the region's diverse regulatory environments, invest in home-based care solutions, and capture the growing demand for evidence-based advanced wound therapies, the pathway to sustained growth in Europe's advanced wound care market is increasingly clear.