How to Design Cross-Chain RWA Tokenization Without Breaking Compliance and Investor Eligibility Rules
Learn how to design cross-chain RWA tokenization with investor eligibility, compliance controls, portable identity, and secure asset transfers across multiple blockchains.
 imdanielsmith
Real-world asset tokenization is moving beyond simply putting bonds, funds, real estate, or commodities on a blockchain. In 2026, the harder problem is making those assets portable across blockchain networks without losing the legal, compliance, and investor-eligibility controls attached to them.
That changes how RWA Tokenization Development Services should be designed. A token cannot be treated like a standard ERC-20 asset that can move freely between wallets and chains. If the underlying asset is subject to securities restrictions, KYC requirements, accreditation rules, transfer limits, or jurisdiction-specific ownership rules, those conditions must travel with the asset.
Recent tokenization research highlights the same architectural challenge: compliance, identity, transfer restrictions, custody, and corporate actions become significantly more complicated once an RWA operates across multiple networks.
Start With Investor Eligibility, Not the Blockchain
A common mistake in RWA Tokenization Development Services is selecting Ethereum, an L2, or another chain before defining who can legally own the asset.
The better approach is to create an investor eligibility matrix first.
For every target market, define:
-
Investor type: retail, accredited, qualified, or institutional
-
Permitted jurisdictions
-
KYC/KYB requirements
-
AML and sanctions-screening requirements
-
Minimum investment or holding limits
-
Transfer restrictions
-
Lock-up periods
-
Tax and reporting requirements
-
Whether secondary-market trading is permitted
The token contract can then enforce these requirements instead of leaving them entirely to an exchange or administrator.
This is particularly important for tokenized securities. The SEC's 2026 statement makes clear that changing the format of a security into a crypto asset does not remove the underlying securities-law obligations.
Use a Hybrid Architecture for Cross-Chain RWAs
Cross-chain RWA infrastructure should not assume that everything needs to live on-chain.
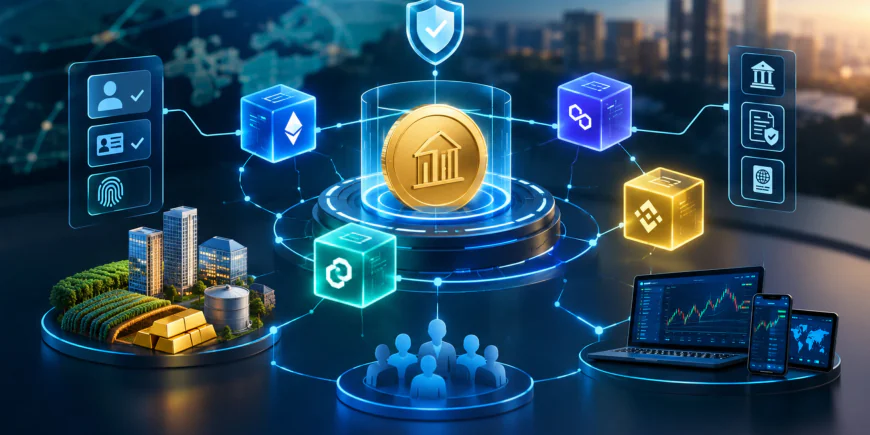
A more resilient architecture separates the system into three layers:
1. Legal and asset layer: An SPV, issuer, custodian, fund administrator, or other legal structure establishes the investor's rights to the underlying asset.
2. Compliance layer: KYC/KYB providers, sanctions screening, accreditation verification, jurisdiction rules, investor classifications, and transfer policies determine whether a transaction is permitted.
3. Blockchain layer: Smart contracts manage token issuance, ownership, transfers, redemption, settlement, and cross-chain movement.
This hybrid model is becoming important because research into RWA architectures shows that blockchain frequently handles representation and transfer while legal rights, custody, verification, and compliance remain partly off-chain.
For RWA Tokenization Development Services, this separation also makes regulatory changes easier to implement without rebuilding the entire token infrastructure.
Make Compliance Travel With the Token
The biggest cross-chain risk is creating a compliant token on one network and then allowing a bridge to create an unrestricted version somewhere else.
Instead, eligibility should be checked at every transfer and every cross-chain mint.
For example:
-
Investor completes KYC.
-
The investor receives a verified identity credential.
-
The compliance engine determines that the investor is eligible for a specific asset and jurisdiction.
-
The wallet is associated with the appropriate permission or attestation.
-
The token contract validates eligibility before transfer.
-
If the asset moves to another chain, the destination token inherits the same restrictions.
-
Any subsequent transfer is checked again.
Emerging compliance-oriented token standards and architectures are exploring embedded identity hooks, transfer restrictions, partitions, forced transfers, and jurisdiction-specific rules for exactly this reason.
The objective is not merely interoperability. It is compliant with interoperability.
Choose the Right Cross-Chain Transfer Model
Not every RWA should use a traditional lock-and-mint bridge.
For regulated assets, the architecture should maintain a single authoritative supply and ownership model. Depending on the asset, this can involve:
-
Lock-and-mint
-
Burn-and-mint
-
Native multi-chain issuance
-
Canonical token plus representations
-
Permissioned interoperability networks
The critical requirement is preventing duplicated claims.
If 1,000 tokenized bonds exist on Chain A and 600 are moved to Chain B, the system must be able to prove that the total economic claim remains 1,000—not 1,600.
Cross-chain infrastructure therefore needs synchronized supply controls, authenticated messages, replay protection, destination-chain eligibility checks, and auditable transaction histories.
Treat Investor Identity as a Portable Credential
Repeatedly performing full KYC every time an investor changes chains creates friction and encourages workarounds.
A better model is portable compliance credentials.
Instead of storing sensitive personal information directly on-chain, the platform can maintain an off-chain identity record while using verifiable attestations or permission states on-chain.
For example:
“Wallet X has passed KYC, is eligible for jurisdiction Y, qualifies as investor type Z, and may hold Asset A until date B.”
The smart contract does not need the investor's passport or residential address. It only needs a trusted proof that the relevant eligibility conditions have been satisfied.
This approach supports privacy while allowing exchanges, custodians, wallets, and tokenization platforms to share compliance signals.
Design Corporate Actions Across Chains
Cross-chain RWA infrastructure also needs to handle what happens after the token is issued.
Interest payments, dividends, redemptions, voting, maturity events, splits, and forced transfers cannot depend on a single-chain architecture.
For example, if a tokenized private-credit instrument pays quarterly interest, the asset-servicing system should identify eligible holders across supported networks, calculate their entitlement, and distribute settlement assets without creating duplicate claims.
This is one reason institutional tokenization is increasingly being designed as an end-to-end financial infrastructure rather than a token-minting exercise.
Build the Compliance Engine as an Upgradeable Component
Regulations and investor eligibility rules will change. Hard-coding every jurisdictional rule directly into immutable contracts can therefore create an expensive migration problem.
A better design uses configurable policy modules with controlled governance.
The platform should support:
-
Jurisdiction-specific transfer rules
-
Blacklist and sanctions updates
-
Investor-class restrictions
-
Transfer caps
-
Holding-period enforcement
-
Emergency freezes
-
Forced transfers where legally required
-
Role-based administrative permissions
-
Auditable rule changes
The goal is to make compliance programmable without making governance uncontrolled.
Where Debut Infotech Fits
Building this architecture requires more than smart-contract development. RWA Tokenization Development Services need to connect token contracts with identity, compliance, custody, asset servicing, cross-chain messaging, and secondary-market infrastructure.
Debut Infotech can approach RWA platforms as a complete financial technology stack—from token issuance and permissioned wallets to compliance workflows, cross-chain infrastructure, and trading integrations.
For platforms that eventually require secondary-market infrastructure, cryptocurrency exchange software development can also become part of the architecture, provided the exchange layer respects the same investor eligibility and transfer restrictions as the underlying token.
Final Takeaway
Cross-chain RWA tokenization should not be designed around the question, “How do we move this token to another blockchain?”
The better question is:
“How do we move the asset while preserving the same legal rights, investor eligibility, supply controls, and compliance conditions?”
That distinction will define the next generation of RWA Tokenization Development Services. As tokenized funds, credit, Treasuries, commodities, and other institutional assets expand across multiple networks, interoperability alone will not be enough. The winning infrastructure will make compliance, identity, custody, and transfer restrictions portable alongside the asset itself.