Canada Packaging Market Size Trends, & Demand Forecast 2034
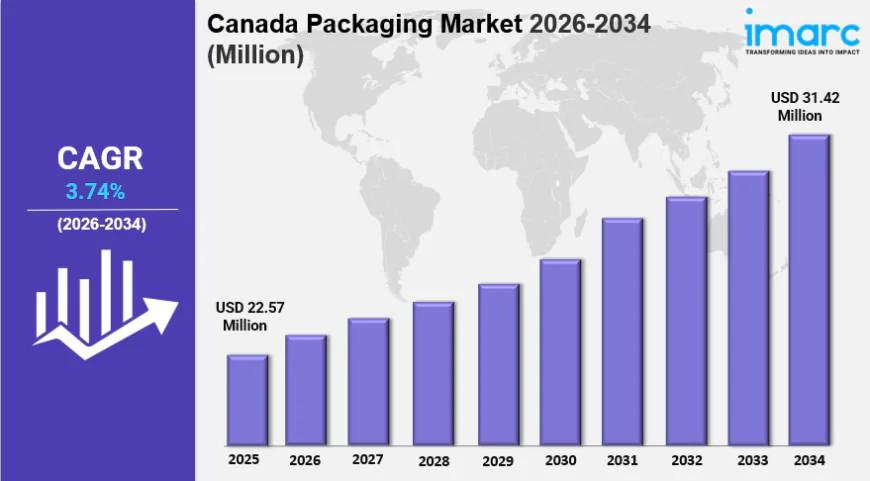
The Canada packaging market reached USD 22.57 Billion in 2025 and is projected to reach USD 31.42 Billion by 2034, growing at a CAGR of 3.74%.
 Nitin Sharma-1
IMARC Group has recently released a new research study titled "Canada Packaging Market Report by Packaging Type and Region, 2026-2034," offers a detailed analysis of the market drivers, growth opportunities, trends and competitive landscape to understand the current and future market scenarios.
Paper Packaging in Canada Outlook 2034: Opportunities for Packaging Stakeholders
The Canada packaging market reached USD 22.57 Billion in 2025 and is projected to reach USD 31.42 Billion by 2034, growing at a CAGR of 3.74% during 2026 to 2034. Within it, paper and paperboard hold a 31.6% share and are the fastest-growing packaging type at approximately 4.1% CAGR, so the canada paper packaging market size is expanding faster than the wider industry. This canada paper packaging market growth is backed by strong food and beverage demand, rapid e-commerce expansion, rising consumer and regulatory pressure for sustainable materials, and the integration of smart packaging technology.
Key Market Statistics at a Glance
Base Year: 2025
Historical Years: 2020-2025
Forecast Period: 2026-2034
Market Size (2025): USD 22.57 Billion
Projected Size (2034): USD 31.42 Billion
Growth Rate: CAGR of 3.74%
Paper and Paperboard Share (2025): 31.6%
Paper and Paperboard Growth Rate: Approximately 4.1% CAGR
Explore Growth Opportunities in the Canada Packaging Market. Grab Your Sample Report: https://www.imarcgroup.com/canada-packaging-market/requestsample
How E-Commerce and Sustainability Are Shaping Canada Paper Packaging Market Trends
Brand owners, food processors and online retailers are looking for recyclable, protective packaging that reduces plastic use and meets provincial rules. This is lifting canada paper packaging market demand for corrugated shipping cartons, paper-based mailers and paper takeaway formats.
Key Market Trends:
• Sustainable Material Transformation: Federal single-use plastics rules, provincial Extended Producer Responsibility (EPR) programs and brand owner sustainability commitments are pushing portfolios toward recycled, bio-based and compostable options, with paper gaining ground in retail shelf packaging, takeaway containers and personal care secondary packaging.
• E-Commerce Packaging Design Optimization: Right-sized packaging, paper mailers replacing polybag mailers, paper cushioning replacing expanded polystyrene, and resealable or returnable formats are attracting investment from Canadian converters serving direct-to-consumer supply chains.
• Corrugated Box-on-Demand and Digital Printing: Engineered fluting, water-based adhesives and digital printing are enabling exact-fit cartons produced on demand, which removes void fill and trims shipping volume.
• Smart Labelling and Traceability: QR codes, NFC tags and RFID are supporting recall management, anti-counterfeiting and consumer engagement, while Health Canada serialization requirements and the Canadian Food Inspection Agency traceability framework are speeding adoption in regulated sectors.
Paper Packaging in Canada: Key Drivers and Strategic Insights for Businesses
A mix of food industry, retail and regulatory factors is fueling canada paper packaging market growth. Understanding these drivers helps businesses gauge how the canada paper packaging market size may evolve and where to focus converting, sourcing and distribution efforts.
Key Growth Drivers:
• Food and Beverage Industry Growth: A Farm Credit Canada report notes that the country could add USD 40 billion to GDP if the sector grows 3% annually, and the sector consumes an estimated 55-60% of total packaging output across fresh, processed, dairy, meat, seafood and beverage categories.
• E-Commerce Expansion: In December 2024, e-commerce represented 6.1% of Canadian retail sales, with online retail sales of roughly USD 3.14 billion, keeping canada paper packaging market demand strong for corrugated cartons, mailers and protective packaging.
• Sustainability and Eco-Friendly Material Shift: The Single-Use Plastics Prohibition Regulations, EPR programs in Ontario, British Columbia and Quebec, and retail chain sourcing policies are requiring producers to reformulate packaging toward compliant alternatives.
• Smart Packaging and Technology Integration: Pharmaceutical serialization and tamper-evident packaging, along with modified atmosphere and active packaging for shelf-life extension, are raising packaging value per unit.
Strategic Insights:
• Capitalize on Paper's Faster Growth: With paper and paperboard at approximately 4.1% CAGR, canada paper packaging market growth outpaces the overall industry, which rewards early capacity and capability investment.
• Prepare for Plastic-to-Paper Substitution: Retail shelf, takeaway food and personal care secondary packaging are the categories where sustainability-led substitution is most visible.
• Manage Input and Recycling Risks: Pulp price spikes, logistics cost inflation and fragmented provincial recycling infrastructure can squeeze margins and slow recycled content adoption.
• Follow Bio-Based and Compostable Innovation: Track canada paper packaging market trends in bio-based and compostable materials, where Canada's agricultural feedstock and policy support are creating commercial openings.
Why Packaging Stakeholders Are Investing in Paper-Based Solutions in Canada
Paper-based formats sit at the center of Canada's move away from single-use plastic, which makes the category a dependable focus for converters, brand owners and retailers. IMARC's canada paper packaging market analysis points to regulatory support, strong e-commerce volumes and new sustainable formats that are sustaining canada paper packaging market demand across food, retail and online fulfilment.
Reasons for Investment:
• Regulatory Tailwinds: EPR frameworks that assign recycling costs to producers favor packaging designs with proven recyclability, creating premium positioning for certified recyclable paper solutions.
• Strong Regional Manufacturing Base: Ontario leads with a 38.6% share in 2025, anchored by the Mississauga, Brampton, Hamilton and Guelph corridors, while Quebec at 24.7% benefits from established paper and paperboard manufacturing that draws on provincial forest resources.
• Room for Differentiation: Companies that can document certified recycled content, EPR compliance and lower carbon footprints are better placed to capture canada paper packaging market share with major brand owners and retailers.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=23946&flag=C
Key Players and Recent Developments in Paper Packaging in Canada
A detailed canada paper packaging market analysis of competition shows a moderately concentrated field: the top five companies hold roughly 35-40% of total Canadian packaging revenue, so canada paper packaging market share remains open to hundreds of regional converters. Rivalry also reflects wider canada paper packaging market trends toward certified recycled content and verified recyclability.
• Amcor plc -- Market leader with a broad Canadian portfolio. In January 2026, it joined the City of Ottawa's The Reuse City Canada Project to help cut single-use packaging waste through scalable reuse systems.
• Sealed Air Corporation -- Strong challenger known for food protection packaging in meat and dairy processing, with protective e-commerce packaging growth under its Bubble Wrap brand.
• Wihuri Group -- Strong challenger through its subsidiary Winpak Ltd., which in July 2025 made its Winnipeg, Manitoba site an authorized converter of DuPont Tyvek healthcare packaging.
• Silgan Holdings Inc. -- Challenger with a strong North American metal packaging, closures and dispensing position, plus a growing healthcare packaging presence.
Key Benefits for Stakeholders
• A comprehensive quantitative analysis of historical and current market trends, forecasts and dynamics of the Canada packaging market for 2020-2034.
• The latest information on drivers, challenges and opportunities, helping stakeholders track the canada paper packaging market size and plan accordingly.
• Porter's Five Forces analysis to assess the impact of new entrants, competitive rivalry, supplier power, buyer power and the threat of substitution.
• A competitive landscape view that clarifies the current positions of key players and their canada paper packaging market share.
Author IMARC Group
IMARC Group is a leading market research company that provides data-driven insights and expert consulting services, helping businesses across diverse industries achieve their strategic objectives.
Contact Us
IMARC Group
Email: [email protected]
United States: +1-201-971-6302