


Understanding the User Journey of Loan Against Fixed Deposit: Why the Interest Rates are More Favorable than Personal Loans
Navigating financial needs can be daunting, but understanding the options available empowers you to make informed decisions
 Ananya Kaur
In today's fast-paced world, individuals often find themselves in need of quick cash for emergencies, business opportunities, or other financial needs. While various borrowing options are available, one incredibly beneficial yet often overlooked method is taking a loan against fixed deposit (FD). In this article, we'll walk you through the user journey of obtaining a loan against FD, with a particular focus on why the interest rates associated with this type of loan are typically lower than those of personal loans.
What is a Loan Against Fixed Deposit?
A loan against FD is a secured loan option where you can borrow a percentage of the amount you have depo
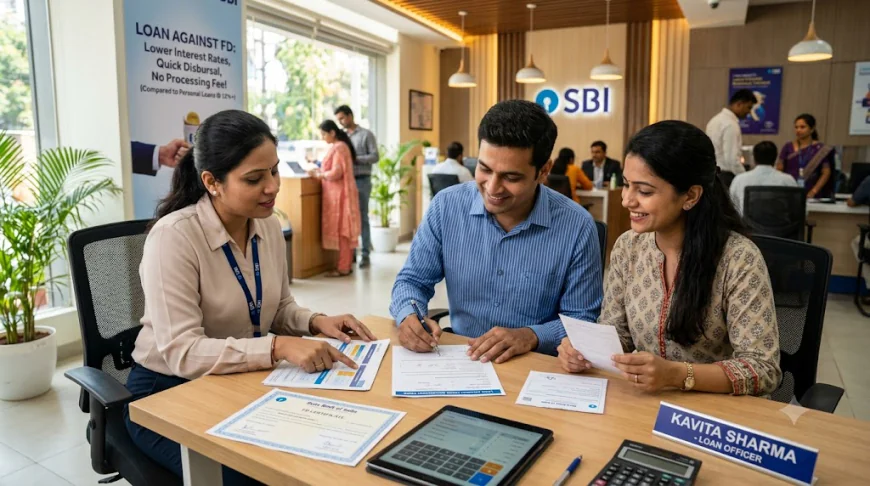
sited in a fixed deposit account at a bank or financial institution. The loan amount is usually up to 90% of the total FD amount, depending on the policies of the lending institution.
Since the loan is secured against your deposit, the risk for the lender is minimized, which in turn results in lower loan on FD interest rates compared to unsecured loans like personal loans.
User Journey: Step-by-Step Process
Step 1: Awareness and Consideration
The first step in the user journey begins with the realization of a financial need. You may have noticed a pressing requirement for funds due to unexpected medical expenses, a long-awaited trip, or even a golden business opportunity.
At this point, you’ll likely explore various options to meet your financial needs. Personal loans may initially seem appealing, but once you review the comparative interest rates, you’ll notice that loans against fixed deposits typically have much lower rates.
Step 2: Researching Loan Options
Once you've recognized your need for a loan, the next step is thorough research. You’ll want to compare different banks and their offerings for loans against FDs. Here, the emphasis should be on the loan on FD interest rate, processing time, and other terms like tenure and repayment options.
Many banks, including major institutions like Axis Bank, offer online calculators that help potential borrowers determine how much they can borrow against their fixed deposits.
Step 3: Assessing Eligibility and Documentation
In this phase, you will evaluate your eligibility to get a loan against your FD. The good news is that if you already have a fixed deposit with the bank you are applying to, the process is relatively simple. Most banks will require minimal documentation since you are using your own funds as collateral.
Usually, you may need to provide:
-
A copy of the fixed deposit receipt.
-
Identity proof (Aadhaar card, passport, etc.).
-
Any additional information that the bank may require.
Step 4: Application Process
Once you have all the documents prepared and an understanding of the terms, the next step is to apply for the loan. Most banks, including Axis Bank, have streamlined their processes and allow customers to apply online or via mobile banking apps.
Step 5: Approval and Disbursement
After your application is submitted, the bank will process it and evaluate your fixed deposit and its tenure. Typically, since these loans are backed by an FD, approval can be very quick, sometimes even within a few hours.
Once approved, the loan amount is credited to your account, allowing you immediate access to funds. This efficiency makes loans against FDs an attractive option for those needing quick finances.
Step 6: Repayment
Repaying a loan against FD generally comes with more flexible options than personal loans. You can choose to repay the loan through EMIs or a lump sum payment, depending on your financial situation.
Since the loan against FD interest rate is significantly lower, your EMI will also be manageable as compared to personal loans, making it a wiser financial decision overall.
Why is Loan Against FD Interest Rate Lower than Personal Loans?
This leads us to the central question: why do loans against FDs come with lower interest rates compared to personal loans? The differences can be attributed to several factors:
1. Secured vs. Unsecured Loans
A loan against FD is a secured loan, meaning that it is backed by the funds in your fixed deposit. If you default on the loan, the bank has the right to seize your fixed deposit to recover the losses. This drastically reduces the risk for lenders, allowing them to offer lower interest rates.
In contrast, personal loans are unsecured, meaning there is no collateral backing the loan. Lenders perceive a higher risk associated with personal loans, leading them to charge higher interest rates.
2. Lower Risk for Lenders
The inherent lower risk in loan against FD translates to lower operating costs for lenders. They spend less on assessing borrower creditworthiness, as the fixed deposit acts as a guarantee of repayment. Therefore, these savings can be passed on to borrowers in the form of lower interest rates.
3. Credit Score Influence
Loans against fixed deposits are less influenced by your credit score compared to personal loans. In personal loan assessments, lenders consider an individual’s credit history, income, and other financial factors in detail, which can result in varied interest rates depending on the borrower's credit profile.
On the other hand, the fixed deposits serve as a strong assurance of repayment, creating a more straightforward application process and lower rates.
4. Ease of Approval
Since the process to get a loan against FD involves leveraging your own funds, it is simpler and much quicker. This ease of approval further reduces administrative costs for banks and leads to lower rates for borrowers with Bajaj Finance.
Conclusion
Navigating financial needs can be daunting, but understanding the options available empowers you to make informed decisions. A loan against fixed deposit presents a compelling alternative to personal loans, highlighting not only the benefits of lower interest rates but also a simplified application process and quicker access to funds.
If you find yourself in a financial pinch, consider the feasibility of utilizing your fixed deposits. With banks like Axis Bank offering reliable services, the journey from need to securing a loan can be seamless and efficient.
Explore your options today, and you might find that a loan against FD is the best solution to your immediate financial needs. Remember, borrowing wisely is key to financial stability, and understanding your choices can help set you on the right path.
For more detailed information and to explore the specifics of a loan against fixed deposit, you can always visit Axis Bank's loan against fixed deposit page.
This comprehensive guide serves as a valuable resource for anyone contemplating financial alternatives, specifically the user journey of acquiring a loan against fixed deposits.




















