Can Australia's Oil and Gas Sector Power Asia's Energy Transition?
Australia's oil and gas market is set to grow from USD 432M to USD 737M by 2034. Explore LNG expansion, decarbonization, and emerging opportunities.
 Ranjeet Sharma
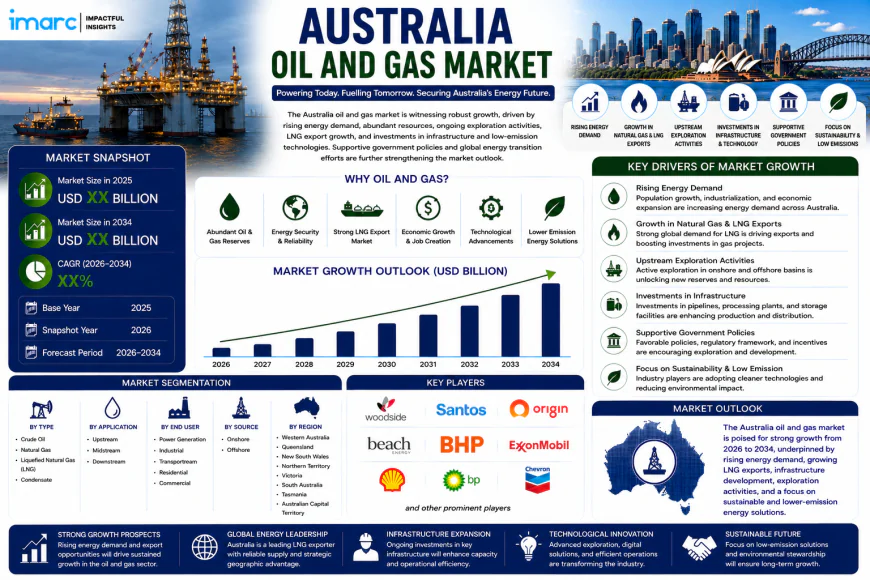
Australian energy executives are navigating a landscape defined by paradox. The nation is one of the world's largest LNG exporters, with over USD 90 billion invested in offshore infrastructure across the North West Shelf, Gorgon, and Wheatstone projects. Yet the sector faces mounting pressure from regulatory uncertainty, environmental opposition, and intensifying global competition from lower-cost producers in the United States, Qatar, and East Africa. The challenge is no longer about finding resources—it is about maintaining competitiveness in a rapidly evolving global energy market. The Australia oil and gas market reflects this complex reality. Growing from USD 432.1 million in 2025 to USD 464.9 million in 2026, the market is projected to reach USD 736.8 million by 2034, exhibiting a compound annual growth rate of 5.93 per cent during 2026-2034. These figures reflect an industry leveraging its established infrastructure and Asian relationships to secure its place in the energy transition.
What's Driving Growth of Australia's Oil and Gas Market?
Asia's coal-to-gas transition is creating sustained demand for Australian LNG. Rapid industrialisation and decarbonisation across major Asian economies are driving structural demand growth for cleaner-burning natural gas. Australia's proximity to Japan, China, and South Korea, combined with decades-long supply relationships, positions the sector as a reliable supplier through the energy transition.
Long-term trade agreements are providing revenue certainty. Australia's strategic diplomatic relationships with Japan, India, China, and South Korea underpin multi-decade LNG supply contracts. These agreements minimise trade barriers, ensure stable revenue for producers, and position Australian gas as a dependable energy source for Asia's evolving energy mix.
Infrastructure investment is enhancing supply chain efficiency. Investments in pipelines, LNG export terminals, and gas processing facilities are improving delivery reliability to both domestic and international markets. These upgrades attract further capital by improving operational scalability and production yield across the value chain.
New offshore developments are extending Australia's production horizon. The Scarborough gas field development by Woodside Energy and the Barossa project by Santos represent significant near-term production additions. New deepwater exploration in the Browse Basin and continued investment in floating LNG technology are unlocking previously stranded gas reserves at commercially viable costs.
Three Trends Reshaping the Industry
Digitalisation and AI are transforming operational efficiency across offshore platforms.
Artificial intelligence, IoT sensors, and predictive analytics are revolutionising upstream exploration accuracy and production optimisation. Operators are deploying AI-enabled predictive maintenance systems that reduce downtime, lower operating costs, and improve safety outcomes across offshore platforms and remote onshore facilities. Digital twin platforms now create real-time virtual replicas of offshore assets, enabling predictive maintenance scheduling and remote operational monitoring.
Why it matters: Digital transformation is compressing operating costs, improving economics for all operators in a high-cost environment.
Business implication: Companies must invest in AI and digital infrastructure or face competitive disadvantage against more agile competitors.
Future impact: Fully autonomous offshore operations will become feasible, reducing human exposure to hazardous environments while improving productivity.
Decarbonisation is reshaping project economics and buyer requirements.
Australian gas producers are investing in low-emission production methods, carbon offset programs, and CCS technology integration to satisfy increasingly stringent carbon credential requirements from Asian LNG buyers. The Gorgon CCS project, one of the world's largest carbon capture initiatives, injects CO₂ into subsurface formations beneath Barrow Island. Government co-investment through CCS and Hydrogen Headstart programs is catalysing private capital mobilisation across low-emission technology projects.
Why it matters: Carbon credentials are becoming a prerequisite for premium market access.
Business implication: Producers must integrate CCS and demonstrate verifiable emissions reductions to maintain relationships with decarbonisation-focused Asian utilities.
Future impact: Low-emission LNG will command premium pricing, creating competitive separation between producers.
Unconventional gas development is gaining momentum as conventional fields mature.
Shale and tight gas development in the Beetaloo and Canning basins is advancing as conventional field maturation creates supply gaps. Advances in horizontal drilling and hydraulic fracturing technology are improving economic viability, offering a pathway to extend Australia's gas production horizon. This emerging segment represents a potentially transformative new supply source for both domestic energy security and export markets.
Why it matters: Unconventional resources could significantly extend Australia's production capacity beyond current conventional reserves.
Business implication: Operators must develop expertise in horizontal drilling and hydraulic fracturing while navigating complex regulatory approvals.
Future impact: Beetaloo Basin development could reshape Australia's gas supply landscape, creating new investment frontiers in the Northern Territory.
What the Market Numbers Actually Tell Us
A market expanding from USD 432.1 million to USD 736.8 million over nine years suggests significantly greater commercial activity across upstream exploration, midstream processing, and downstream LNG export operations. The 5.93 per cent compound annual growth rate signals steady, structural expansion driven by Asian demand and new project commissioning. Upstream leads type segmentation at 50.0 per cent in 2025, driven by exploration and production from Australia's prolific offshore basins. Offshore commands 60.0 per cent application share, reflecting deep-water LNG project concentration. Western Australia dominates the regional landscape with a 40.0 per cent share, underpinned by world-scale LNG infrastructure. For investors and industry participants, the trajectory indicates that oil and gas will remain a cornerstone of Australia's export economy, even as the sector navigates the complex transition toward lower-emission operations.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of energy transition and infrastructure leverage. Hydrogen production represents a strategic opportunity, with Australia positioned to become a major exporter leveraging existing gas infrastructure and abundant renewable energy. Carbon capture and storage offers another compelling pathway, with depleted gas fields providing suitable CO₂ storage sites that enable continued fossil fuel production while meeting emissions obligations. The Beetaloo Basin unconventional gas development in the Northern Territory represents a potentially transformative new supply source. Queensland's coal seam gas fields continue to attract capital for production optimisation and reserve extension drilling supporting the Gladstone LNG complex. Companies that can navigate regulatory complexity, invest in decarbonisation technologies, and maintain competitive unit economics are well-positioned to capture value in this evolving market. Key players including Woodside Energy, Santos, Chevron, BP, and Origin Energy are advancing dual strategies of maximising established LNG assets while building capabilities in hydrogen and CCS.